Tools for your business
Marketing, technology, and operational resources
 First National Real Estate
Tools for your business
Marketing, technology, and operational resources
Priority: AU, Medium, National
👓 2 minute read
One of the hardest conversations in real estate today is explaining why a property may attract interest but struggle to attract an acceptable offer.
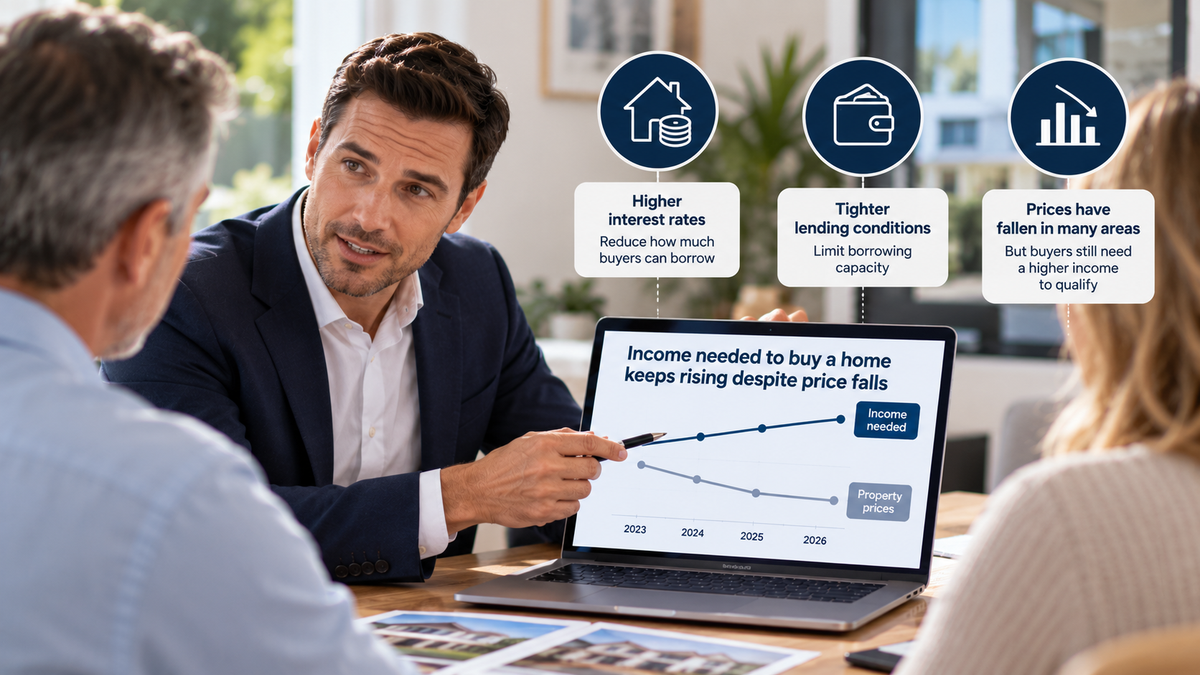
For many buyers, the obstacle isn't a lack of enthusiasm. It's borrowing capacity.
Canstar research shows the income required to qualify for a typical Australian home loan has risen dramatically, even as property prices have fallen. Higher interest rates and lenders' serviceability assessments mean buyers can afford less than they could previously.
For our salespeople, understanding this distinction can make vendor conversations more productive.
Explain what has changed
A vendor may reasonably ask why their home should be worth less when nothing about the property has changed.
The answer lies in the relationship between property value and purchasing power.
A property's location, presentation and features remain important, but its achievable selling price also depends on what qualified buyers can afford and are prepared to pay.
When borrowing capacity falls, the pool of buyers capable of competing at a particular price can shrink.
That doesn't automatically mean every property must be discounted. It does mean agents need to reassess the evidence supporting their price recommendations.
Five ways to approach the conversation
1. Separate interest from purchasing capacity
Explain that enquiry and inspection numbers don't necessarily indicate how many buyers can finance a purchase. Establish whether interested buyers have finance approval, what conditions apply, and whether their budgets have changed.
2. Use current comparable sales
Show vendors what similar properties have actually achieved recently, rather than relying on prices from six or twelve months ago. Explain differences in presentation, location, land, improvements, and selling conditions.
3. Explain the impact of interest rates
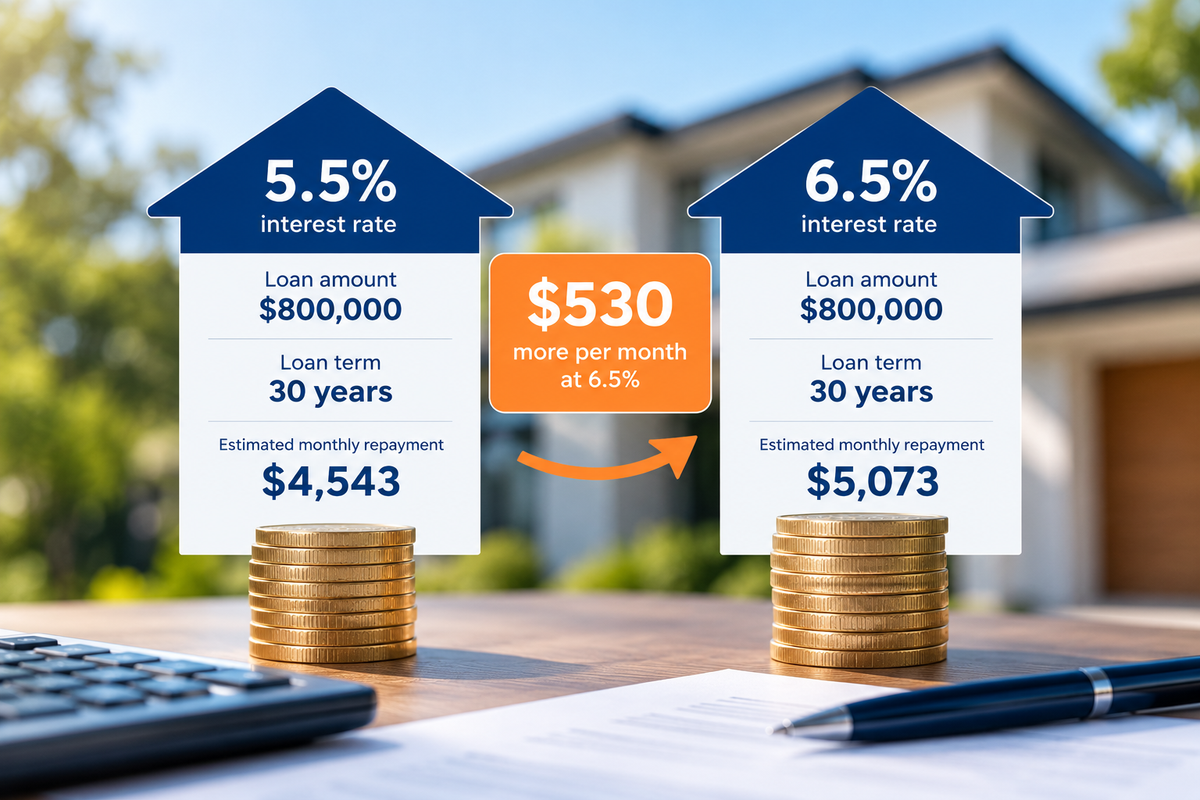
A useful illustration is that a buyer borrowing $800,000 over 30 years would pay approximately $530 more per month at 6.5 per cent interest than at 5.5 per cent.
That difference helps explain why some buyers have reduced their budgets even though their incomes haven't fallen.
4. Distinguish asking prices from market evidence
Competing listings reveal what other vendors hope to achieve. Completed sales reveal what buyers have recently been prepared and able to pay.
Use both, but explain the difference.
5. Present options, not ultimatums
Where a campaign is struggling, discuss the available choices: refreshing presentation, reaching additional buyer audiences, changing the method of sale or reconsidering price expectations.
Explain the likely advantages, costs, and limitations of each option. A price adjustment may be necessary, but it should follow evidence and a considered discussion.
Give vendors an explanation they can use
Consider this approach:
'Your property hasn't lost the features that make it desirable. What's changed is how much many buyers can borrow. Higher interest rates mean some purchasers who could have afforded this home a year ago may no longer qualify for the same loan. Our job is to maximise what today's qualified buyers are prepared and able to pay, then recommend the best strategy to achieve the strongest possible result.'
The objective isn't to persuade vendors that their property has suddenly become less desirable. It's to help them understand the financial constraints affecting today's buyers.
Good agents don't simply report that buyers won't pay more. They help vendors understand why, demonstrate the evidence, show initiative in keeping campaigns active, and recommend a way forward.
Priority: AU/NZ, Medium, National
👓 1 minute read
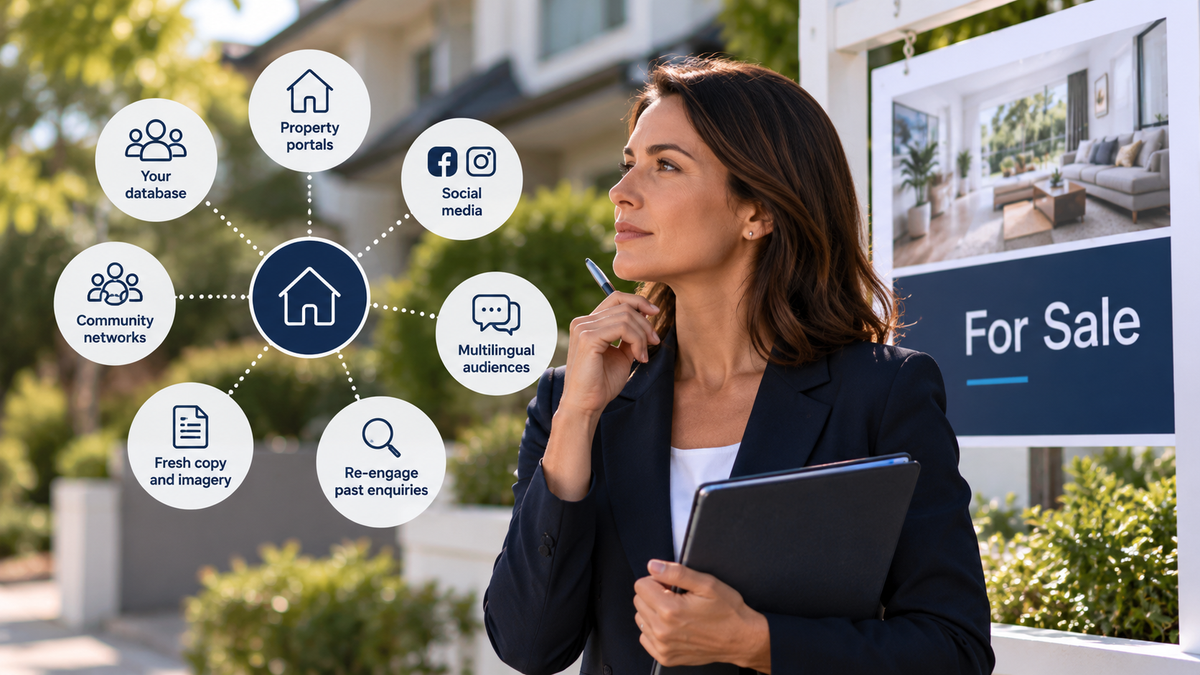
In a tougher market, some listings will inevitably take longer to sell. By week six or eight, the photography has been seen, the database contacted, opens conducted, and buyer feedback discussed. Repeating the same campaign – or simply pushing the vendor for another price reduction – may not create a different result.
Price still matters, and our agents need to be frank when buyer feedback shows a property is incorrectly positioned. But before concluding price is the only lever left, ask another question: have we genuinely reached every likely buyer?
A campaign refresh can start by looking beyond the audience targeted at launch. Consider different social audiences, community networks, multilingual content, your wider buyer database and alternative digital channels. The major portals remain fundamental – the opportunity is to extend their reach rather than replace them. Dive into the FN Prompt Library and make AI your friend in repurposing and re-targeting your campaign to different buyer personas.
It is also worth revisiting the fundamentals: presentation, photography and copy, follow-up with previous enquiries, buyer feedback and your negotiation strategy. Sometimes one of these needs changing before more money is spent on promotion. At the very least, start by immediately changing the hero photographs on all of your stalled listings.
Most importantly, give your vendor a plan. Instead of returning with the same conversation each week, show them what you have learned, what you are changing and which new buyers you intend to reach.
A stalled campaign doesn't necessarily need more of the same. Sometimes the better question is simply: who haven't we marketed it to yet?
Priority: AU/NZ, High, National
👓 1 minute read
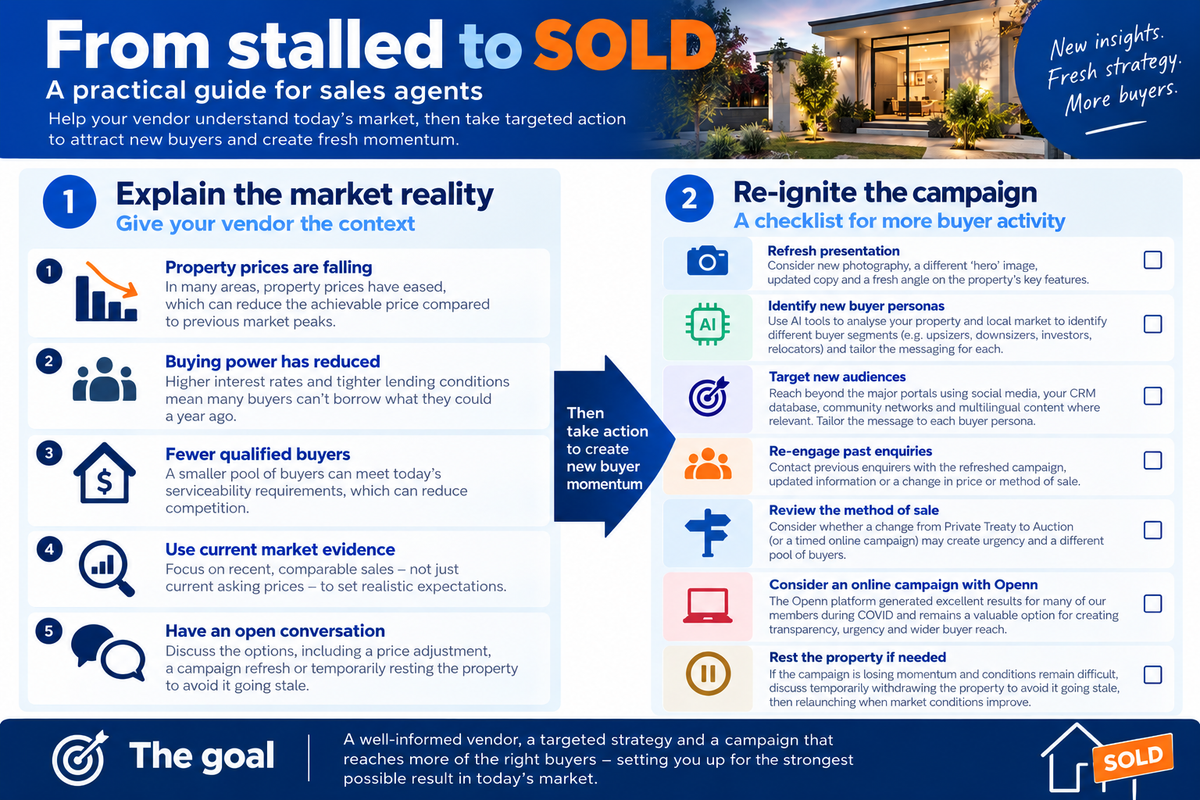
Now is not the time to shrink into the background, waiting for buyers to enquire or vendors to reduce their price. Confront the market head-on and increase the regularity of contact with your vendors, including face-to-face meetings.
In a difficult campaign, the next offer you present matters enormously. Believe it or not, your vendor's belief that you have worked hard to find the best offer matters more than the offer itself.
Stay silent and then suddenly appear with a lower offer, and your vendor will be far less inclined to accept it.
Call several times a week with updates, if only to say there’s been no new buyer enquiry in the last few days - but here’s what I’ve done about it.
Make calls to your buyer database
Talk to other agents in your office about buyers they’re working with
Approach competitor agents to offer conjunctions
Refresh campaign copy and photography
Try a different hero image
Identify different buyer personas and create targeted pitches through social media and your CRM
Letterbox drop around the property to build local awareness
Confront overpricing early and revisit regularly
You could also reconsider the method of sale. Remember how effectively many agents used online negotiation during COVID? Openn Negotiation helped create competitive tension around stalled properties, so don’t sit on your hands.
Activity gets noticed, and not only by your vendors.
Neighbours, owners currently listed with other agencies, and buyers in the market can all see when an agent is working harder to achieve a result. Today's difficult campaign can become tomorrow's reason someone chooses you to sell their property.
Priority: AU/NZ, High, National
👓 1 minute read
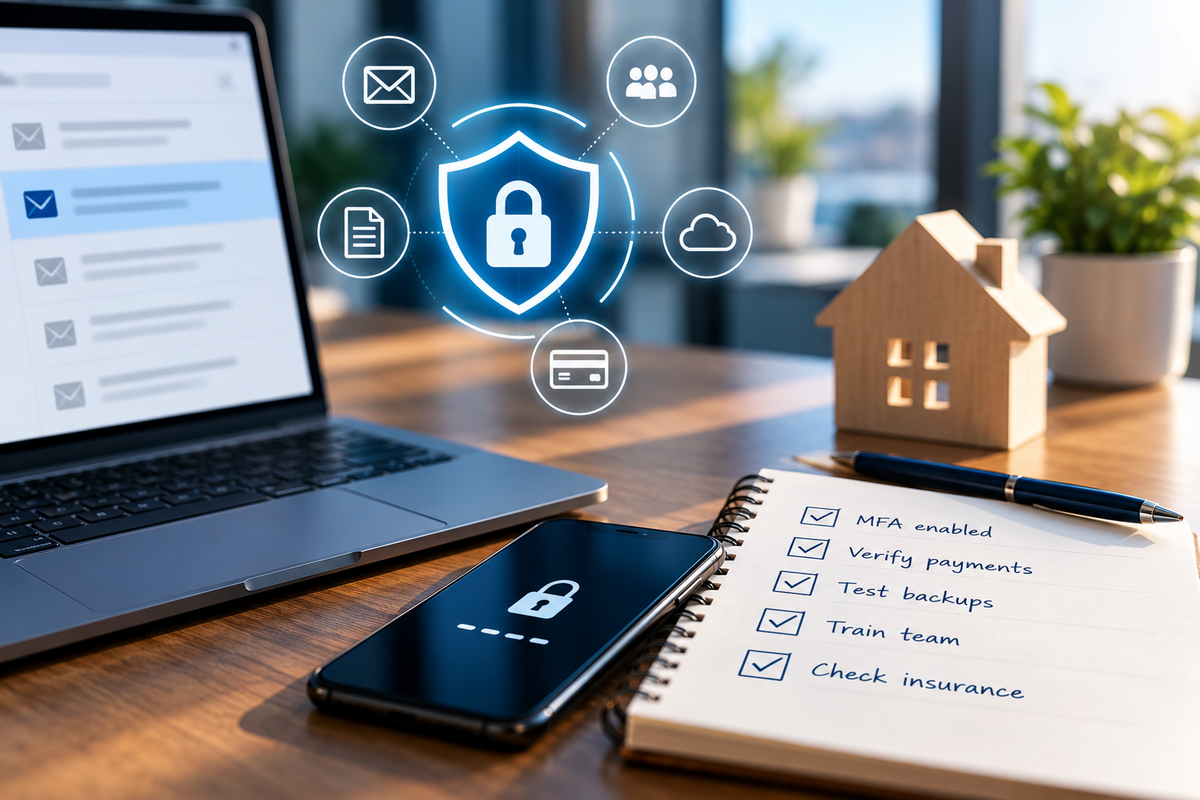
A cyber incident doesn't have to begin with sophisticated hacking. Often, it starts with someone who is busy, distracted or pressured into clicking, approving or paying something they shouldn't.
As part of Cyber Ready, our insurance partner Marsh has identified practical controls real estate businesses can put in place to reduce their exposure to payment diversion, impersonation and ransomware.
1. Protect your accounts
Use multi-factor authentication wherever possible, maintain strong password practices, keep systems patched and watch for unusual mailbox forwarding rules, login activity or security changes.
2. Verify before money moves
Introduce a strict call-back procedure for changed bank details, urgent transfers and unusual settlement instructions. Never rely on the email thread itself to verify the request. For higher-value transactions, Marsh also recommends dual approval and documenting the verification undertaken.
3. Make sure your backups actually work
Backups should be tested and accompanied by a restoration plan. As Marsh puts it, a backup that can't be restored quickly isn't a real control.
4. Train for the human factor
Short, regular training on suspicious emails, payment changes and impersonation attempts is more effective than an annual awareness exercise. Just as importantly, make it easy for staff to report something suspicious quickly without fear of blame.
5. Check your insurance
Preventative controls can't eliminate every cyber risk. Marsh recommends agencies ensure their insurance is appropriate for their exposure and understand what their policies require when an incident occurs.
Cyber security works best when these controls become everyday business practice – verify unusual requests, report suspicious activity early and make sure your team knows what to do before an incident occurs.
Please register your team for our upcoming webinar today.
Explore the Australian Government's resources
Explore the New Zealand Government's resources
Priority: VIC, High
👓 1 minute read
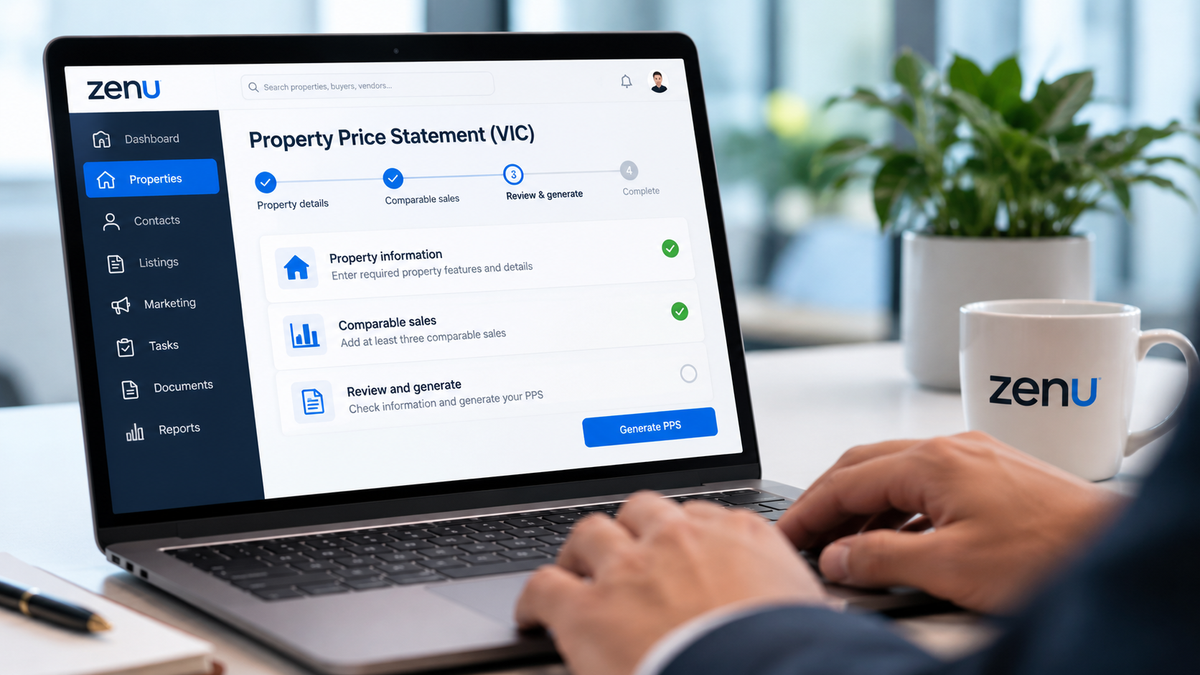
Victorian members using Zenu now have additional safeguards to help manage the new Property Price Statement (PPS) requirements.
The PPS replaced the Statement of Information for residential sales from 1 October, with the new requirements applying to auctions and fixed-date sales from 16 October 2026.
Zenu has responded by building the PPS into its property workflow. Agents can see missing information, enter required property features and comparable sales, and generate the statement from within the platform. It also prompts agents where fewer than three comparables have been provided and includes controls around publication of confidential or exempt sold prices.
Importantly, Zenu will prevent a property progressing beyond Pre-listing until its PPS is complete, adding a practical compliance checkpoint before a property goes to market. Members who prepare their PPS separately can still upload it to Shared Docs.
The recent First National webinar attracted 100 registrations, with 62 members attending and a particularly active Q&A, showing there are still plenty of questions around the changes.